Home Realty Design | Build Surfaces Journal Origins CloseQalc Connect

On Property Tax Context

Every Number Needs an Address

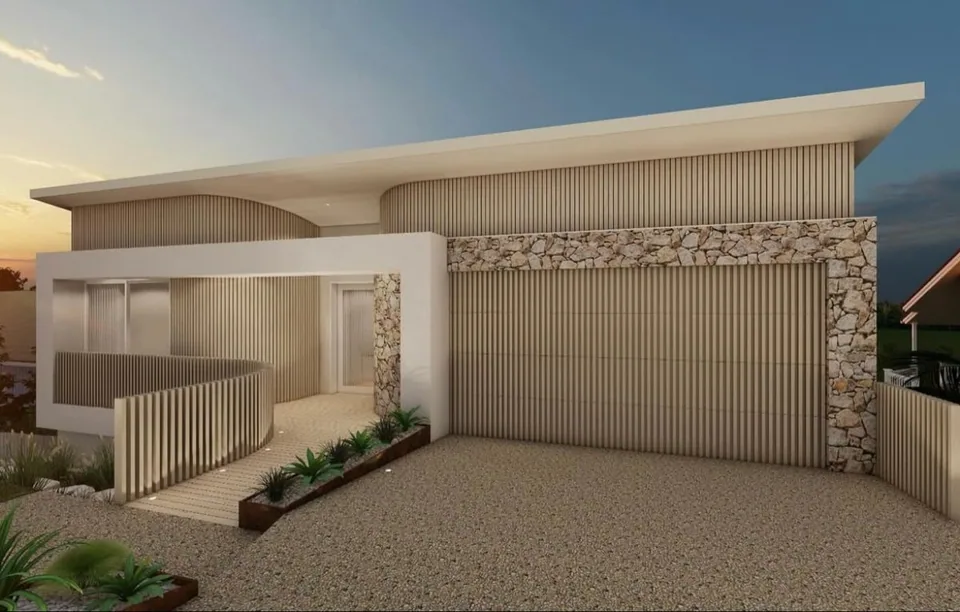
Architectural rendering of a low modern residence with a broad white roof, vertical brown screens, pale stone walls, a curved entry walk, and a sunset sky

Begin with the specific property record and the general tax rate for the same tax year. The effective rate and municipal averages can add context, while a revaluation changes the assessment base; each figure becomes useful only when its address, year, and purpose remain attached.

Begin with the record

The opening visual study shows a low modern residence beneath a broad white roof, with vertical screens, pale stone, and a curved entry walk. It is an architectural rendering, and it is not identified as a B&Co. project, a New Jersey property, or evidence of any assessment. Its role here is simply to hold one address in view while the numbers around an address are separated.

For a Bergen County property, the county Board of Taxation links to a property-record search where a parcel can be found by location, block, lot, or owner name. The site’s property-tax reference explains the useful starting point: the specific assessment and tax record for the address under consideration, rather than a municipal average treated as though it were a bill.

Keep the tax year attached to that record. An assessment, a rate, an average, and a revaluation notice may each describe a different year or stage of the tax cycle. Writing the year beside every figure is a small discipline, but it prevents a current property question from being answered with a number that belongs to another base.

Give each rate one job

The New Jersey Division of Taxation defines the general tax rate as the multiplier used to determine the tax levied on a property. It is expressed per one hundred dollars of taxable assessed value and is the rate used to compute the tax bill. The operation is specific: assessed value and the general rate for the same tax year belong in the calculation.

The effective tax rate does different work. The Division describes it as a statistical study that compares districts on the assumption that each is assessed at one hundred percent of value. That makes it useful for broad comparison across municipal systems, while keeping it outside the arithmetic for a specific property bill.

This rate is NOT to be used to compute the tax bill.

A rate therefore cannot be read as a verdict by itself. Two properties may carry different assessments, and two municipalities may express their tax bases differently. A smaller general-rate number does not establish a smaller bill without the parcel’s assessment, just as an effective rate does not replace the general rate in the bill calculation. The label tells the reader what the number is allowed to answer.

Let the average stay average

The second visual study places an older stone façade with repeated arches beside a tall purple glass volume. It is a separate architectural image, not a property identified for sale, a B&Co. project, or a source of tax information. The contrast is useful because outward appearance can invite a quick comparison even when the records behind two properties may be organized on different terms.
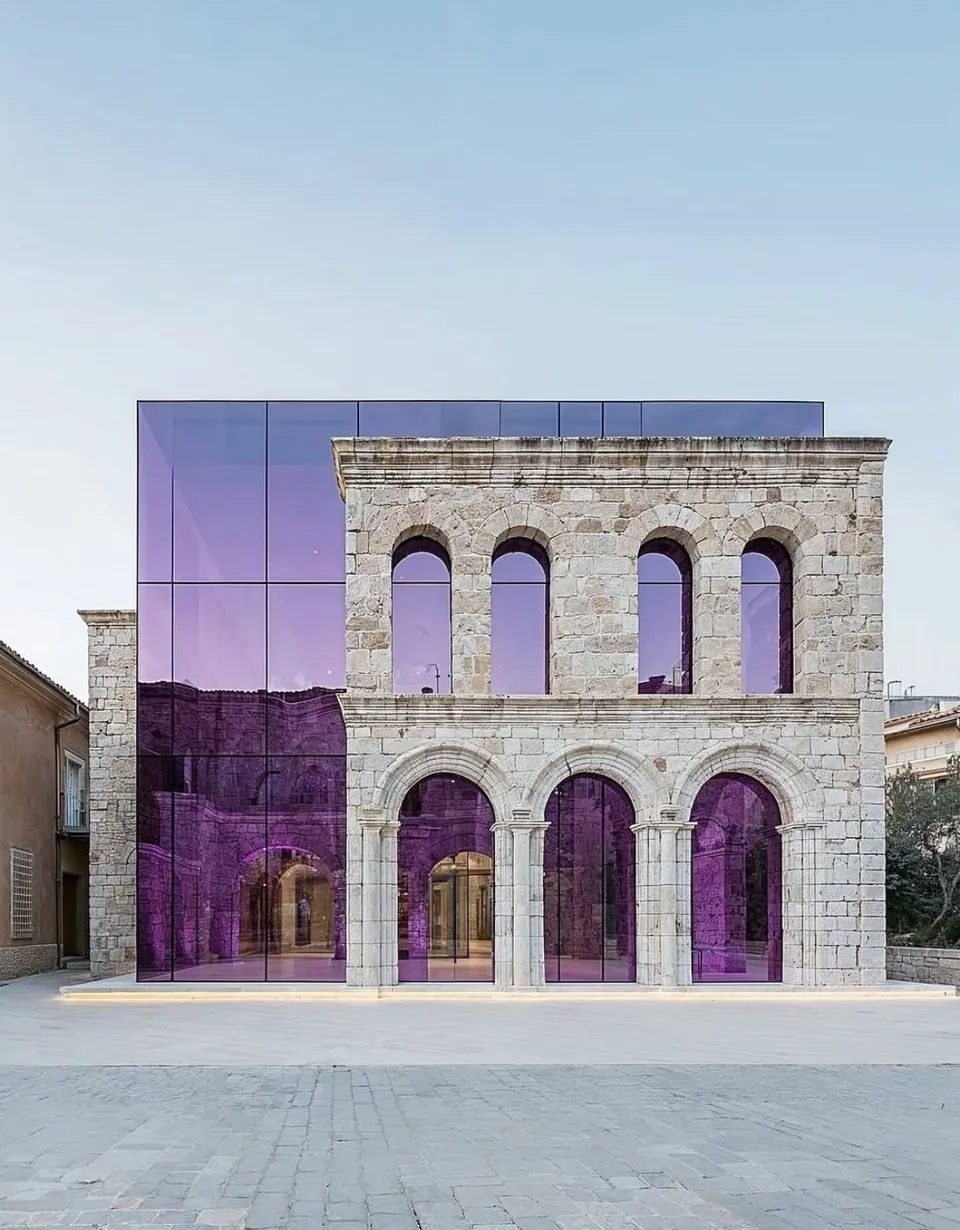
Stone façade with two levels of arched openings beside a tall purple glass volume across a paved forecourt

The State’s average residential statistics describe a municipality’s residential line items for the year shown. An average assessment and an average bill can place a townwide figure in context, but neither one states what a particular parcel is assessed or billed. The average remains a description of the set, even when one address happens to sit near it.

That distinction changes the quality of a property conversation. A municipal average can frame a question about whether an address is above or below a broad reference point. The property record then supplies the parcel’s answer. Used in that order, context helps the reader notice what deserves explanation without turning a townwide statistic into a substitute for the document attached to the property.

Read revaluation as redistribution

A revaluation introduces another number that needs its proper job. The Division says a revaluation program seeks to spread the tax burden equitably within a municipality. Its worked example doubles the municipality’s aggregate assessments without increasing the total taxes collected; the tax rate falls proportionately. The example is a warning against treating a higher assessment, by itself, as a forecast of the next bill.

The useful reading is relational. The new assessment belongs beside the new municipal base and the rate produced for that base, not beside an earlier rate as though nothing else changed. This does not predict any property’s outcome. It keeps the comparison internally consistent, which is the minimum required before the number can inform a real decision.

Property-tax context becomes clearer when every figure keeps its address, year, and purpose. The parcel record answers the parcel question. The general rate performs the calculation. The effective rate and municipal averages provide wider context. Revaluation explains a change in the base. With those jobs kept separate, the numbers stop competing and begin to describe the same property from the right distance.

← All of the Journal Begin a Conversation →